Venture capital is a form of private equity financing that investors provide to startup companies and small businesses judged to have long-term growth potential, in exchange for an equity stake. Because early-stage companies often lack the track record or collateral needed for traditional bank loans, venture capital fills a critical funding gap between personal savings and public markets.
Origins: ARDC and Georges Doriot
Modern venture capital traces to 1946, when Harvard Business School professor Georges Doriot co-founded American Research and Development Corporation (ARDC) alongside Ralph Flanders and Karl Compton. ARDC was notable for raising money from a broad pool of institutional investors rather than relying on a single wealthy family’s fortune, a structural innovation that became the template for the venture capital industry that followed.
The Digital Equipment Corporation breakthrough
ARDC’s defining success came in 1957, when it invested roughly $70,000 for a 70 percent stake in a new company called Digital Equipment Corporation (DEC). When DEC went public in 1966, the value of ARDC’s stake had grown enormously, demonstrating to the broader investment community that venture-backed startups could produce extraordinary returns and helping legitimize venture capital as a distinct asset class.
Fund structure
Venture capital firms typically organize as limited partnerships. General partners manage the fund and make investment decisions, while limited partners, often pension funds, university endowments, and wealthy individuals, supply most of the capital but take a passive role. General partners earn both a management fee on assets and a share of profits, commonly called carried interest, once the fund returns capital to its limited partners.
Investment stages
Venture capital flows to companies in stages that roughly track a startup’s maturity. Seed funding supports very early product development, often before a company has significant revenue. Series A funding typically follows once a company has found some early traction, with Series B, C, and later rounds supporting further scaling as the business grows and its valuation increases.
Venture capital and Silicon Valley
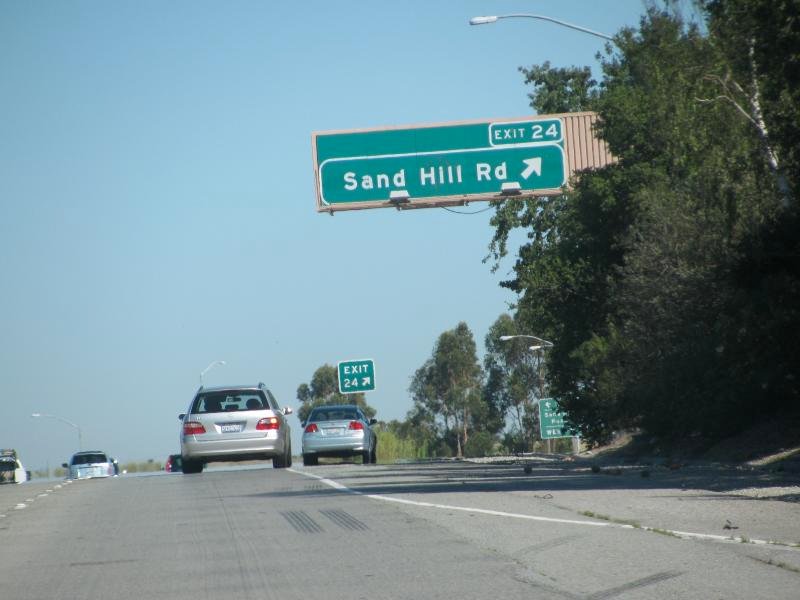
Venture capital became closely associated with the growth of Silicon Valley from the 1970s onward, as firms along Sand Hill Road funded successive waves of semiconductor, personal computing, internet, and software companies. The close geographic concentration of venture capitalists, engineers, and research universities in the Bay Area helped create a self-reinforcing ecosystem that venture capital historians often credit as central to the region’s technological rise.
Risk and returns
Venture capital investing follows a power-law pattern in which most individual investments fail to return their original capital, while a small number of breakout successes generate the overwhelming majority of a fund’s overall profit. This dynamic shapes how venture capitalists operate, pushing them toward portfolios of many bets rather than a few safer ones, and explaining their willingness to accept a high failure rate among individual portfolio companies in pursuit of rare, outsized winners.
Exit strategies
Venture capitalists generate returns through an eventual exit, most commonly an initial public offering, in which the startup’s shares begin trading on a public stock exchange, or an acquisition, in which a larger company buys the startup outright. Exits convert the fund’s equity stake into cash or publicly tradable shares that can be distributed to limited partners, and the timeline to a successful exit, often seven to ten years or more, is a key reason venture capital is considered a long-horizon, illiquid investment.
Venture capital versus other funding sources
Venture capital differs from other common funding sources in important ways. Angel investors, often wealthy individuals investing their own money, typically write smaller checks at earlier stages than institutional venture funds. Bank loans require collateral and predictable cash flow that early-stage startups usually lack. Crowdfunding platforms raise smaller amounts from many individual backers. Venture capital occupies a distinct niche, offering larger sums in exchange for equity and active involvement, often including board seats and strategic guidance, in a company’s direction. Many venture-backed companies first demonstrate traction through a minimum viable product before pursuing this kind of institutional funding.
Due diligence and term sheets
Before investing, venture capital firms conduct due diligence, examining a startup’s financials, market opportunity, team, and legal standing. If the firm decides to proceed, it issues a term sheet outlining the proposed investment amount, valuation, and rights granted to investors, such as board representation or liquidation preferences, which set the framework for the more detailed legal agreements that follow.
Criticism of venture capital
Critics argue venture capital’s pursuit of rapid, outsized growth can push founders toward unsustainable expansion or short-term decisions that prioritize the next funding round over long-term stability. Others note that venture funding remains geographically and demographically concentrated, with a large share historically flowing to startups in a small number of hubs and to founders from narrow networks, prompting ongoing efforts to broaden access to venture capital.
Corporate venture capital
Beyond independent venture firms, many large corporations operate their own venture capital arms, investing company funds in startups that align strategically with their core business. Corporate venture capital gives startups access to an investor’s industry expertise, distribution channels, and potential partnership opportunities, though it can also raise questions about competitive conflicts of interest that independent venture firms do not face in the same way.
Venture capital outside the United States
While the United States, and Silicon Valley in particular, remains the largest venture capital market, the industry has expanded substantially in regions such as China, India, and Europe over the past two decades, with local venture ecosystems developing their own networks of funds, accelerators, and exit markets tailored to regional regulatory and economic conditions.
FAQs
What was the first institutional venture capital firm?
American Research and Development Corporation (ARDC), founded in 1946 by Georges Doriot and colleagues, is widely credited as the first.
What is the difference between a general partner and a limited partner in a venture fund?
General partners manage the fund and make investment decisions, while limited partners provide most of the capital but do not participate in day-to-day management.
Key facts
- The first institutional venture capital firm, American Research and Development Corporation (ARDC), was founded in 1946 by Georges Doriot; ARDC's roughly $70,000 investment in Digital Equipment Corporation in 1957 became one of the most profitable early venture investments after DEC's 1966 IPO.
Related concepts
In the news
Quick checkWho is considered the father of venture capital?Show answer
Georges Doriot, a Harvard Business School professor who co-founded American Research and Development Corporation (ARDC) in 1946, the first institutional venture capital firm.
Sources
- Harvard Business School historical collections on Georges Doriot and ARDC; National Venture Capital Association; Digital Equipment Corporation company history
Editorially reviewed by Specialty Digest Editorial TeamLast reviewed November 1, 2026Researched and drafted with AI assistanceReport an issue