A balance sheet is a financial statement that lists what a company owns, what it owes, and the owners’ residual stake in it, all as of one specific date. Unlike statements that cover a period of activity, a balance sheet is a snapshot: it freezes a company’s financial position at the close of a single day, usually the end of a fiscal quarter or year.
History of the balance sheet
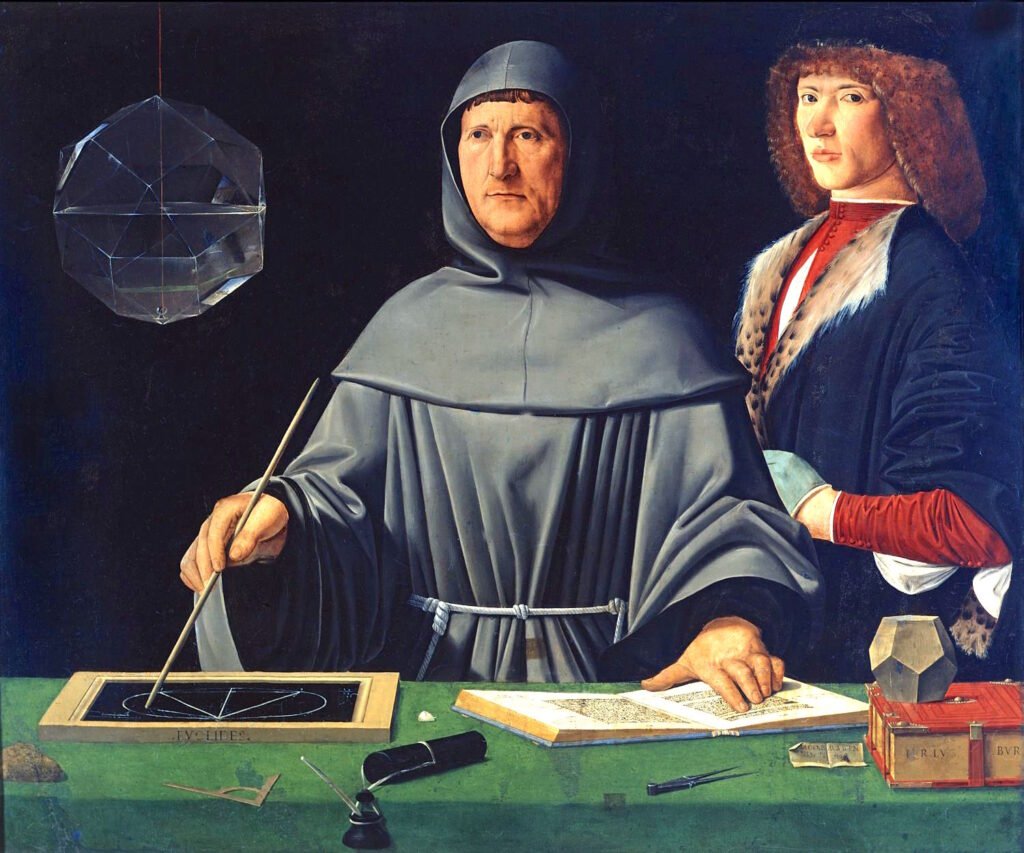
The balance sheet rests on double-entry bookkeeping, a method of recording each transaction as both a debit and a credit so the two sides of the ledger stay in balance. Merchants in Italian trading cities had used some version of this method since at least the 13th century, refining it through generations of practice rather than through a single inventor. The Italian merchant and mathematician Luca Pacioli did not invent double-entry bookkeeping, but he gave it its first printed description. [2]
His 1494 textbook, Summa de arithmetica, geometria, proportioni et proportionalita, was published in Venice by Paganino Paganini in an edition of roughly 1,000 copies, of which about 120 are known to survive today. An identical second edition followed in Toscolano in 1523. Written in vernacular Italian rather than Latin, it served merchants and students across northern Italy as both a textbook and a reference work. [2]
Its business-focused section, Particularis de computis et scripturis, set out trial balances, balance sheets, and other tools that professional accountants still rely on. A similar method had already been described in an unpublished 1458 manuscript by the merchant Benedetto Cotrugli, but that work circulated far less widely and had little influence. Because Pacioli’s book standardized and spread accounting practice so effectively, he is often called the father of accounting, even though he recorded an existing craft rather than inventing a new one. [2]
How a balance sheet works
Every balance sheet rests on one equation: assets equal liabilities plus owners’ equity. Assets are the resources a company controls and expects to bring future economic benefit, including cash, inventory, equipment, and buildings. Liabilities are obligations the company must eventually settle, such as loans, unpaid supplier bills, and bonds outstanding. Owners’ equity is the residual claim left over once liabilities are subtracted from assets, representing what owners would theoretically keep if the company sold every asset and settled every debt. [1]
Because the equation must always balance, any increase in equity has to be matched by an equal increase in the company’s net assets. Within both assets and liabilities, accountants separate current from noncurrent items. Current assets, such as cash, accounts receivable, and inventory, are expected to convert to cash or be used up within roughly one operating cycle. Noncurrent assets, including land, buildings, intangible assets, and long-term investments, are held for longer. Current liabilities, amounts owed to suppliers, employees, and tax authorities, fall due in the near term, while noncurrent liabilities, mainly long-term bonds and pension obligations, extend further into the future. The difference between current assets and current liabilities, known as working capital, is a common measure of short-term financial flexibility. [1]
Types of equity on a balance sheet
Owners’ equity is not a single figure. In the United States, it typically splits into paid-in capital, the money a company has raised by selling shares, and retained earnings, the accumulated profit left after dividends are paid out over the company’s life. Some accounting systems divide equity differently; much of continental Europe, for example, separates restricted equity that cannot be distributed to shareholders from unrestricted equity that can. A sole proprietorship or partnership tracks equity instead through owner or partner capital accounts rather than shares. [1]
Companies that report under US GAAP or International Financial Reporting Standards must present a balance sheet, called a statement of financial position under IFRS, as part of every full set of financial statements, alongside an income statement and a cash flow statement. [1]
Applications and examples of the balance sheet
Investors read a balance sheet to judge solvency, the ability to meet long-term obligations, and liquidity, the ability to meet short-term ones. A bank reviewing a loan application checks the balance sheet to see how much debt a borrower already carries relative to its assets and equity. Company management uses it to track whether growth is being funded by new debt, by retained profit, or by new share issues.
Because the balance sheet, income statement, and cash flow statement describe the same underlying business from different angles, analysts read them side by side rather than in isolation. A retailer preparing to borrow for a new warehouse, for instance, will show the loan as a new long-term liability once funds arrive, matched by the building as a new noncurrent asset, while the interest expense flows separately through the income statement in later periods.
Why the balance sheet matters
A balance sheet shows the accumulated effect of every financing, investing, and operating decision a company has made since it began, information no single transaction can reveal on its own. Its main limitation follows directly from this strength: because it is a snapshot, a balance sheet cannot show how a company’s position is trending without an earlier period’s statement for comparison, and figures can shift sharply around a reporting date in ways that make typical debt or cash levels look better or worse than they usually are.
Balance sheet vs. income statement
The balance sheet and the income statement answer different questions about the same company. A balance sheet reports financial position at a single date: what a company owns, owes, and is worth in book terms at that moment. An income statement reports financial performance over a period, typically a quarter or a year, by setting revenue against expenses to arrive at net income. The two connect directly: the net income an income statement reports for a period flows into retained earnings, one of the equity accounts on the balance sheet that follows it.
Key facts
- The accounting equation behind every balance sheet is assets equals liabilities plus owners equity.1
- Its first published description appeared in Luca Pacioli's 1494 textbook Summa de arithmetica, printed in Venice in an edition of about 1,000 copies, of which roughly 120 survive.2
- Assets and liabilities are each split into current and noncurrent categories, and the gap between current assets and current liabilities is called working capital.1
- Under IFRS the balance sheet is formally named the statement of financial position.1
Related concepts
In the news
Quick checkWhat equation underlies every balance sheet?Show answer
Assets equal liabilities plus owners' equity, so any change in equity must be matched by an equal change in net assets.
Sources
- Encyclopaedia Britannica. The balance sheet. Undated (accessed 1 November 2026)
- Wikipedia. Summa de arithmetica. Undated (accessed 1 November 2026)
Editorially reviewed by Specialty Digest Editorial TeamLast reviewed November 1, 2026Researched and drafted with AI assistanceReport an issue